Retention drops a point and nobody knows which calls were missed
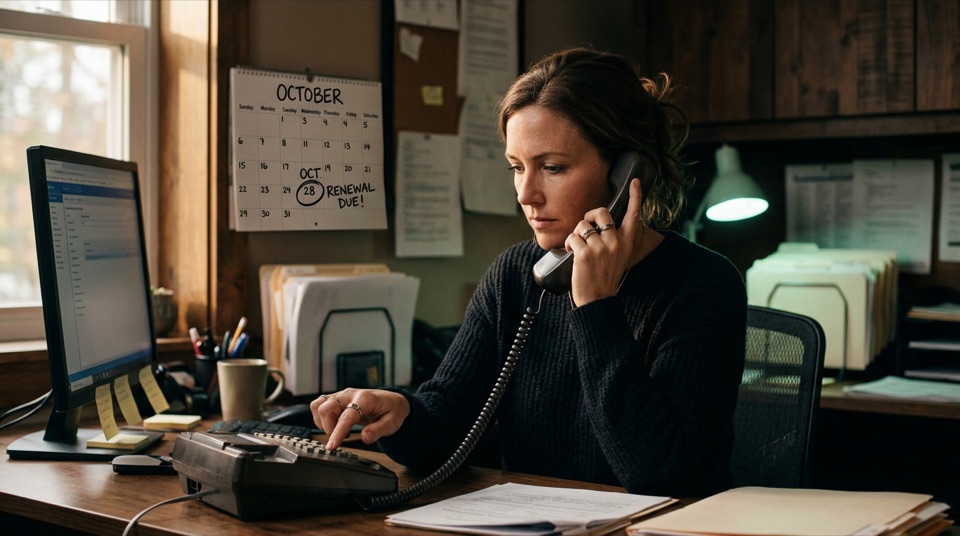
The renewal comes up. The rate is higher, because the rate is higher everywhere. The carrier sends the letter. Your office sends nothing, or sends a templated email. Three weeks later the household has a new agent, and you find out when the cancellation request arrives. Multiply by every rate increase in the book and retention drops a point, then another.
Each of those households cost you money to write the first time. Replacing them means buying leads, quoting shoppers and binding at whatever rate your producers bind at. Keeping them would have cost one phone call. The call did not happen because nobody in the agency was assigned to it, and because nobody could see it had not happened until the household was gone.
80% of sales are made between the 5th and 12th follow-up attempt, and 48% of salespeople never follow up at all (from the Million Dollar Follow-Up course). Renewals are follow-up. An agency that never calls its own book is in the 48%.
The renewal is a sales call, so treat it like one
Service staff treat renewals as paperwork. Producers treat them as somebody else's job. Both are wrong. A household facing a rate increase is deciding whether to stay, and the agency that talks to them first usually wins that decision. That is a sale, and it needs the same structure, practice and scoring as a new quote.
The structure is straightforward. Open by naming the increase before the customer does. Review what changed and what did not: the coverage, the claims, the drivers, the roof. Explain the increase in one plain sentence. Then move to what you can do: discounts they have not taken, a deductible adjustment, the second policy that lowers the total household cost. Close by asking them to stay and confirming the renewal. Book the next review before hanging up.
Write your version of that call down. Use your carriers' language for the discounts and your own voice for the rest. That document is what producers learn, what they practice against and what real renewal calls are scored on.
- Name the increase before the customer does
- Review what changed and what did not
- Explain it in one plain sentence
- Find the discount, the deductible or the second policy
- Ask them to stay and book the next review
Assign it and put a clock on it
Renewals fail on ownership. Decide who calls: producers on their own households, a dedicated retention role, or a split by premium size. Then decide when. The call should land before the rate letter, or the day it lands, not when the cancellation request arrives. Put the households with increases above a threshold on a list every Monday and give each one a name and a due date.
Then make the list visible. If a producer's renewal calls are just one more item in a CRM, they get skipped for the new quote that feels more urgent. If the calls are a daily task that shows up on a score the producer can see, they get made. In Revenue OS, daily tasks are 25% of a producer's Compliance Score, recalculated nightly, so a skipped renewal week shows up on the number the next morning.
Practice the increase conversation before the real one
Producers avoid renewal calls because the calls are uncomfortable. "Why did my rate go up $40?" "I have never had a claim." "My neighbor pays less." A producer who does not have answers for those puts the call off, and off, until the letter does the talking.
Rehearse them. An AI customer can play the angry long-term policyholder at three difficulty levels, by text or live voice, and score each run in about 60 seconds on script adherence, objection handling, close attempt, energy and tone, and follow-up setup, with a coach's note. Ten minutes a day for two weeks and the increase conversation stops being the call producers dread and becomes one they can run without a script in front of them.
Score the real renewal calls
Renewal calls should be recorded with consent and scored like quotes. In Revenue OS the Intel Suite scores every call on six skills, including value stacking and follow-up setup, plus your renewal process at 60% weight, with the best and worst moment timestamped. A call under 80 becomes a redo due 6pm the next business day against an AI customer seeded with the real policyholder's words.
For the household that went quiet after the increase, the Deal Helper takes a description of the stalled renewal and returns three named follow-up plays with exact words and the reason each works, with the outcome logged per producer. Over a quarter that log tells you which plays keep households in your market, and which producers are actually working their book.
What you get is a retention number you can explain. Not "retention was down a point," but "forty households had increases, thirty-one got a call before the letter, twenty-six stayed, and here are the nine that were never called." That is a number you can move next month, and moving it is how an agency breaks its revenue record without buying a single extra lead.
The short version
- The renewal is lost when the rate letter arrives before your call, so the call has to come first.
- Treat the renewal as a sales call with a written structure: name the increase, review, explain, find the saving, ask them to stay.
- Assign every increase to a name and a due date, and put the calls on a score so skipping them is visible.
- Practice the increase conversation daily and score the real calls so weak ones become a redo, not a lost household.
Questions owners ask
When should an agency call a customer about a rate increase?⌄
Before the rate letter arrives, or the same day. The household decides whether to stay in the days after they see the new number, and the agent who explains it first usually keeps them. Waiting for a cancellation request means calling a customer who has already found another quote and now sees your call as damage control.
Who should own renewal calls in an insurance agency?⌄
Someone specific, by name, for every household on the list. Producers on their own book, a dedicated retention role or a split by premium size all work. What does not work is leaving renewals as shared paperwork. Put the calls on a daily task list that feeds a visible score so a missed week shows up the next morning.
What should a producer say when a customer asks why their premium went up?⌄
Name the increase, review what changed and what did not, and explain it in one plain sentence. Then move to what the agency can do: discounts not yet taken, a deductible adjustment or a second policy that lowers the household's total cost. Ask them to stay and book the next review. Rehearse it before the real call.
See how the system runs in Insurance.
Revenue OS for InsuranceYour best month ever, and the plan to beat it.
Break Your Revenue Record